By Archford Chirimudombo
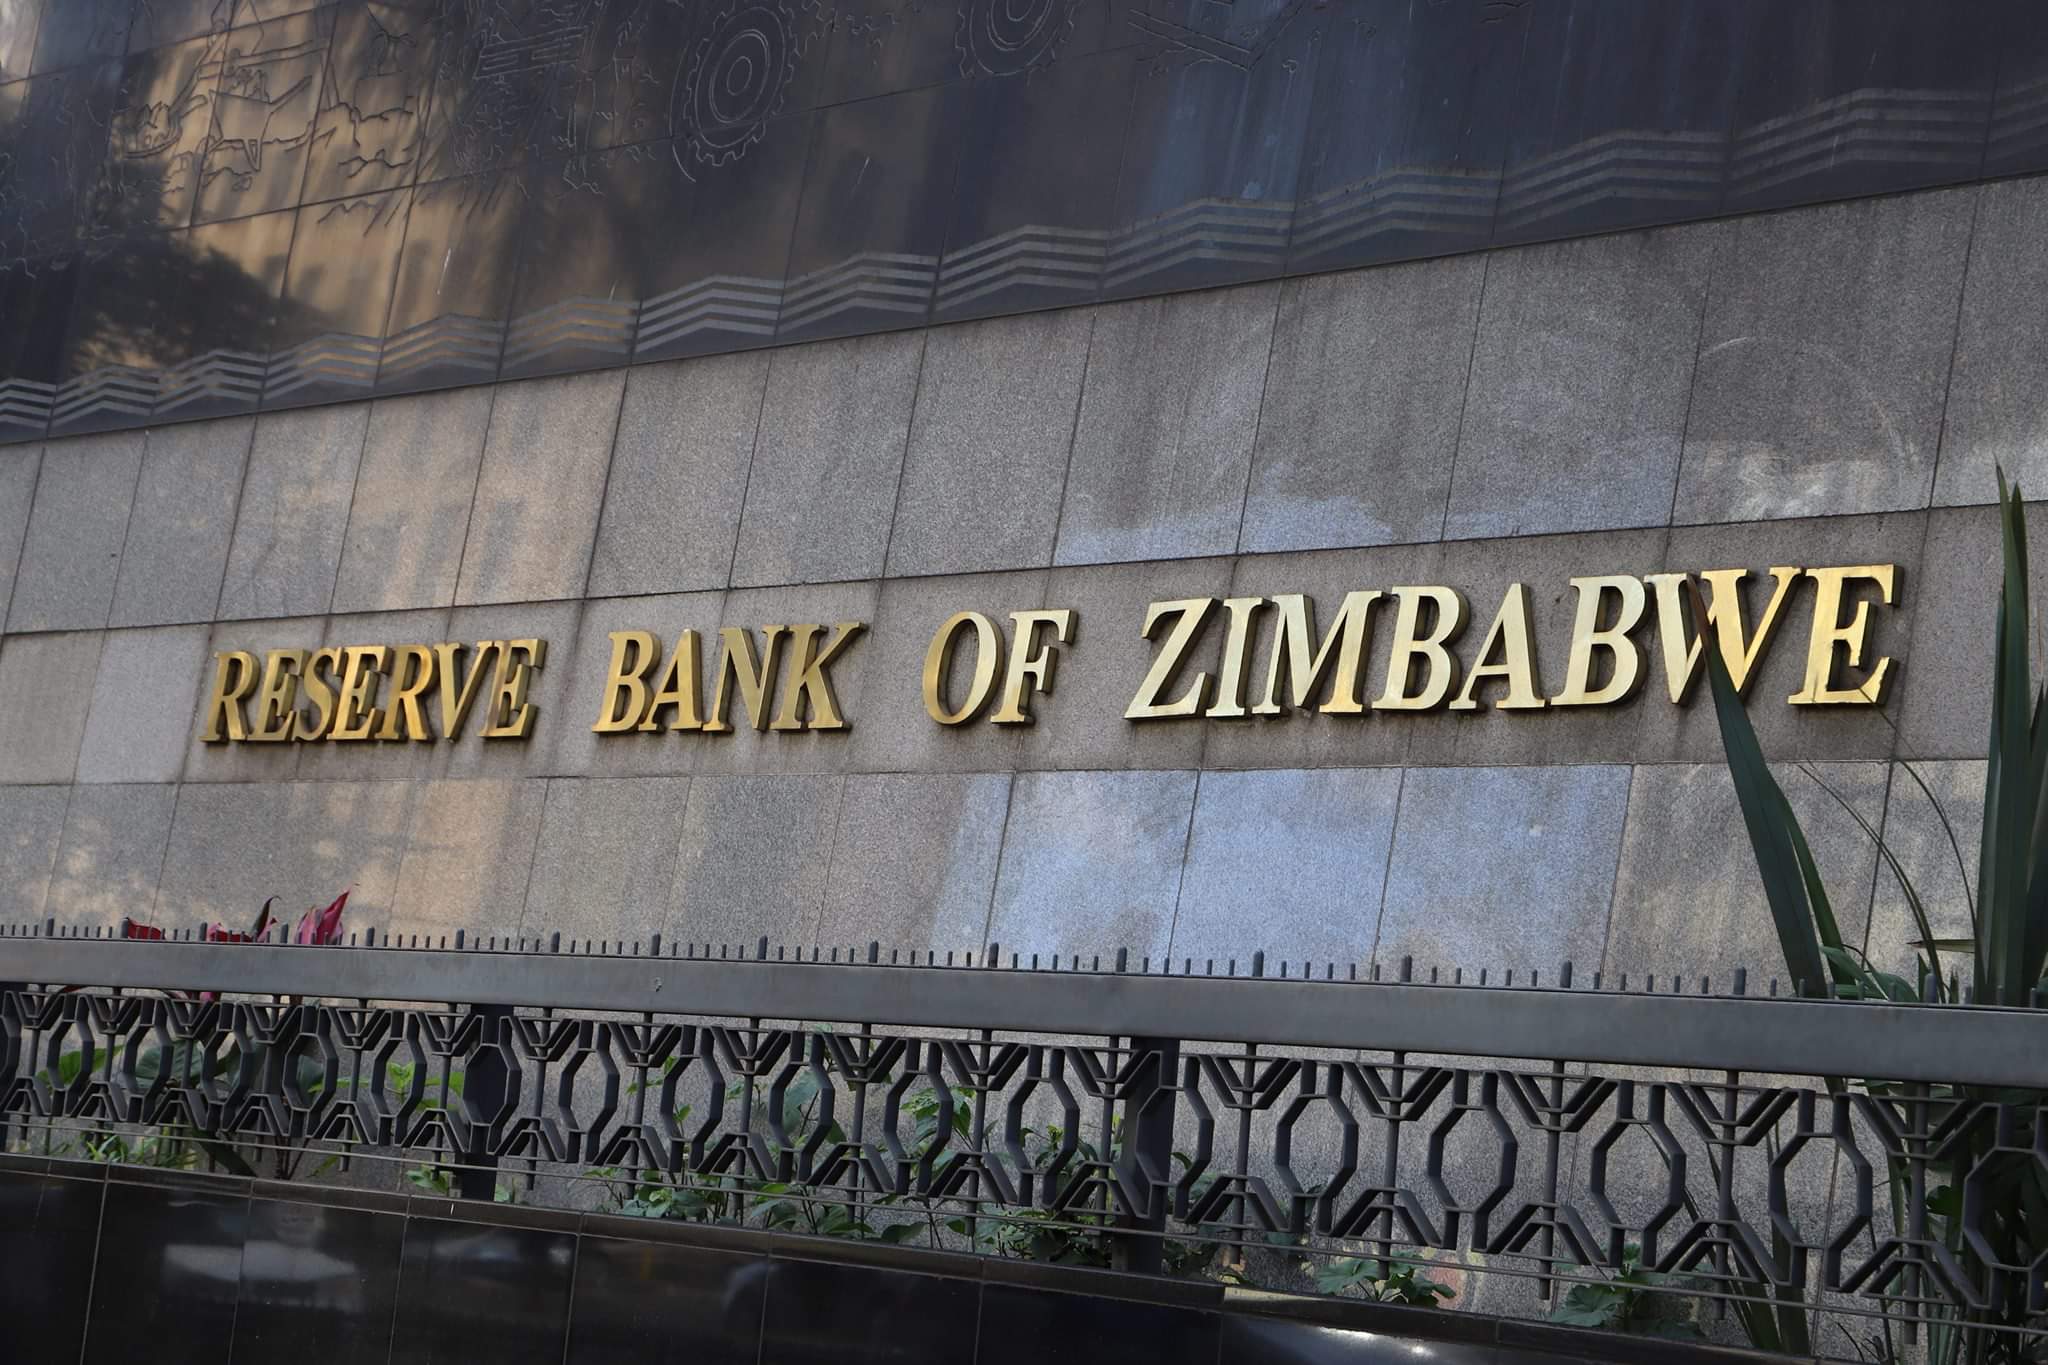
Harare, September 29, 2026 (New Ziana) – Zimbabwe’s economy is on course to achieve the initially projected five percent growth in 2026, underpinned by strong performance in the mining and agriculture sectors, the Reserve Bank of Zimbabwe’s Monetary Policy Committee (MPC) has said.
The MPC reached the position at its meeting in Harare on Monday, where it reviewed recent macroeconomic and financial developments and assessed the outlook for the economy.
In a statement, RBZ Governor Dr John Mushayavanhu said the committee welcomed continued stability in prices, and the exchange rate, which had helped anchor inflation and exchange-rate expectations.
Annual ZiG inflation fell to 2.9 percent in August 2026, its lowest level since 1980, before edging up to 3.7 percent in September.
“The increase largely reflected the renewed rise in international oil prices, which exceeded US$100 per barrel on 9 September 2026, amid the escalating conflict in the Middle East. Inflation expectations have, however, remained well anchored with month-on-month inflation averaging 0.4 percent for the period from January to September 2026. This translates into an annual average inflation of 4 percent.
“The stable price conditions have been supported by prudent money supply management, with reserve money contained within the targets agreed between the RBZ and the International Monetary Fund (IMF) under the ongoing ten-month Staff Monitored Programme (SMP). Accordingly, annual inflation is expected to remain in single digit levels, at below 7 percent by the end of 2026,” Dr Mushayavanhu said.
The central bank said the improving economic environment was also reflected in stronger foreign currency inflows, which rose 37.8 percent to US$14.3 billion in the eight months to August 2026, from US$10.3 billion recorded during the corresponding period last year.
According to Dr Mushayavanhu, the increase was largely driven by higher export earnings, particularly from mining, as well as diaspora remittances.
“Export receipts more than offset the increase in imports, arising from higher international oil prices. Preliminary estimates indicate that the current account recorded a surplus of US$1.1 billion in the first half of 2026, a substantial improvement from the US$248.2 million surplus recorded in the corresponding period of 2025. The current account surplus is projected to strengthen from US$2.1 billion in 2025 to US$3.5 billion in 2026.
“The strong external position supported the accumulation of foreign currency reserves backing ZiG, which exceeded US$2 billion in September 2026, equivalent to about two months of import cover. Increased foreign currency inflows have also enhanced the availability of foreign currency in the interbank market, underpinning the stability of the exchange rate within the ZiG27-27 per US$1 range in 2026,” he said.
Against the backdrop of subdued inflation and continued economic growth prospects, the MPC resolved to reduce the RBZ’s Bank policy rate from 30 percent to 27.5 percent with immediate effect.
The latest reduction brings the cumulative cut in the policy rate to 7.5 percentage points since June 2026.
The MPC also reduced the interest rate on the Targeted Finance Facility (TFF) from 15 percent to 12.5 percent, while capping banks’ all-inclusive lending rate to productive sectors at 22.5 percent.
At the same time, the committee retained the existing differentiated statutory reserve requirements at 30 percent for demand deposits and 15 percent for savings and time deposits.
The MPC also resolved to maintain the minimum interest rates on savings and time deposits at their current levels and continue issuing the ZiGDTDF to support the development of the yield curve for domestic local-currency instruments and promote domestic savings.
Dr Mushayavanhu stressed that the reduction in the policy rate should not be interpreted as a shift towards monetary easing.
“The MPC further emphasized that the reduction in the Bank policy rate does not signal monetary easing, but a realignment of the policy rate to the observed inflation dynamics. In this context, the MPC has embarked on a gradual path of monetary policy normalisation against the backdrop of entrenched macroeconomic stability and better-anchored inflation expectations.
“The pace of monetary policy adjustment will remain dependent on prevailing monetary and financial conditions, taking into consideration uncertainties arising from climatic shocks and geopolitical tensions,” Dr Mushayavanhu said.
New Ziana